News
Totaled by a Delivery Van on Eastern Boulevard: Your Options When the Insurance Payout Won't Cover Your Loan in Alabama
By Benjamin Schoettker | J.D. | Barfoot & Schoettker, LLC | 25+ years | Personal Injury, Wrongful Death, Slip and Fall, Premises Liability, Car Accidents, 18-Wheeler Accidents, Motorcycle Accidents
Published: 2026-10-15 | Last updated: 2026-10-15
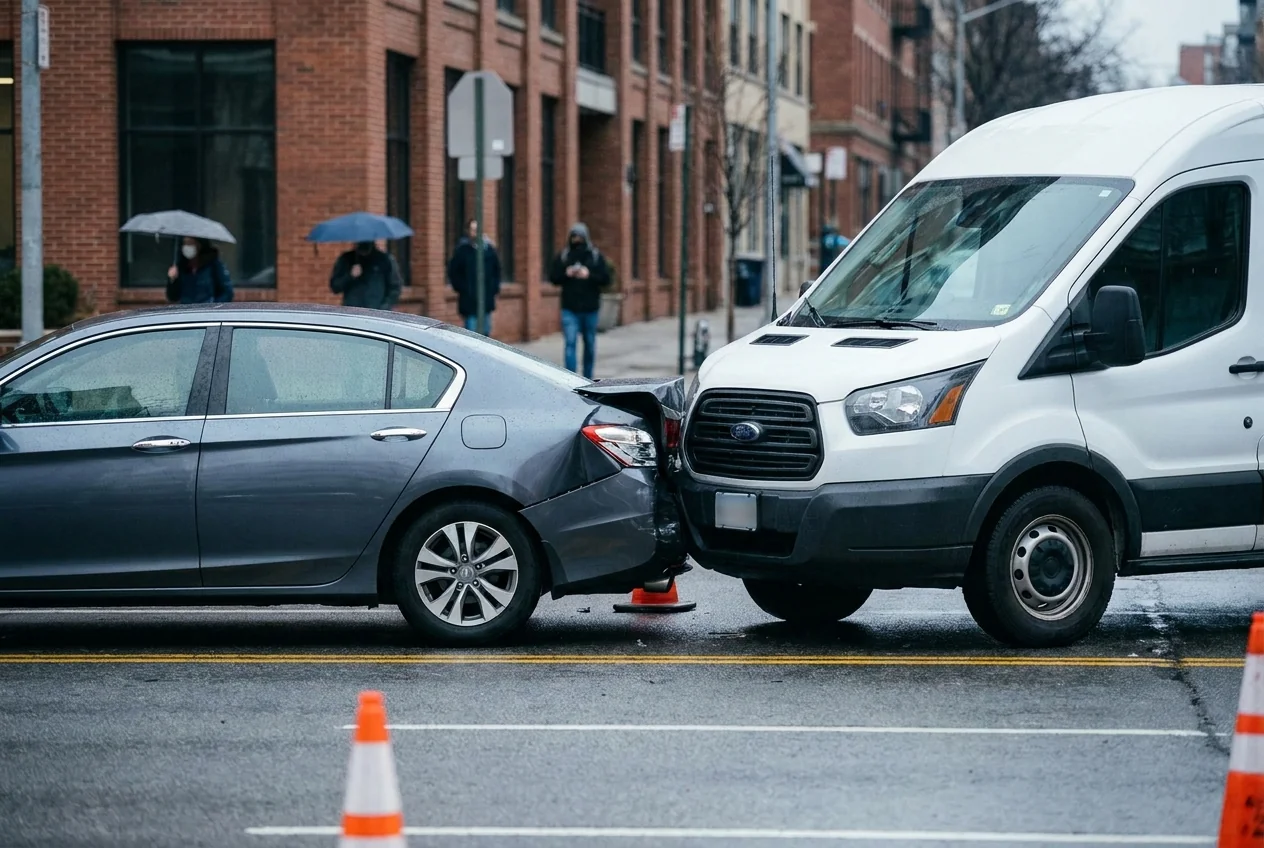
TL;DR: Getting rear-ended by a delivery van on Eastern Boulevard is bad enough. Finding out the at-fault driver's insurer wants to pay you thousands less than what you still owe on the loan is a second injury.
Getting rear-ended by a delivery van on Eastern Boulevard is bad enough. Finding out the at-fault driver's insurer wants to pay you thousands less than what you still owe on the loan is a second injury. Here is the piece most drivers do not realize until it happens to them: under Alabama law, when your vehicle is a total loss, the insurance company owes you the actual cash value (ACV) of the car at the moment of the wreck — not what you owe the lender, and not what you paid for it two (2) years ago. The gap between those numbers is yours to deal with unless you plan for it.
Insurers typically run your car through valuation software that pulls comparable sales, applies condition adjustments, and spits out a number. Those programs often lowball the Montgomery market, pull comps from far outside our area, or ding your vehicle for 'condition' without ever looking at it. You can push back. Pull your own comparable listings from local dealers and private sellers for the same year, make, model, trim, and mileage. Document your maintenance records, recent tires, and any options the software missed. A written counter-demand with real comps often moves the number. Ultimately, the carrier has to justify its valuation, and when the comps do not support it, the offer tends to come up.
If you carry gap insurance on your loan, this is exactly what it is for — it covers the difference between the ACV payout and your remaining loan balance. Check your own policy and your lender's paperwork before you assume you do not have it; gap coverage is sometimes bundled into the financing without the buyer remembering. You also have another option many people do not realize: in most total-loss situations you can keep the vehicle as a salvage buy-back. The insurer pays you the ACV minus the salvage value, you take a salvage title, and you decide whether to repair it or sell it for parts. Whether that math works depends on the damage.
While Alabama's contributory negligence rule can bar recovery when the injured driver is even slightly at fault, a rear-end collision by a delivery van usually puts fault squarely on the other driver. That matters because the at-fault carrier — not just your own — is on the hook for your property damage, your diminished value if the car had been repairable, a rental while you are without transportation, and any personal injuries. It is important to note that accepting a quick property-damage check does not waive your injury claim, but you should read any release carefully before you sign anything. When the numbers do not add up, do not sign.
“The insurance company's first offer on a total loss is almost never their last offer. When drivers come in with local comps and maintenance records, the valuation usually moves — sometimes substantially. The carrier has to justify its number, and software printouts are not the final word in Alabama.” — Benjamin Schoettker, Barfoot & Schoettker, LLC
Frequently Asked Questions
My car was totaled by a delivery van that ran into me on Eastern Boulevard. The insurance company offered me way less than what I owe on it. What are my options in Alabama?
Getting rear-ended by a delivery van on Eastern Boulevard is bad enough. Finding out the at-fault driver's insurer wants to pay you thousands less than what you still owe on the loan is a second injury.
Does the at-fault driver's insurance have to pay off my car loan?
No. Alabama law entitles you to the actual cash value of the vehicle at the time of the wreck, not your loan balance. If you owe more than the ACV, that gap is yours unless you have gap insurance covering the difference.
Can I keep my totaled car in Alabama?
Usually yes. In most total-loss claims you can elect a salvage buy-back, where the insurer pays the ACV minus the salvage value and you keep the vehicle on a salvage title. Whether that makes financial sense depends on the damage and repair cost.
Hurt or Shortchanged After a Wreck on Eastern Boulevard?
If a delivery van or commercial vehicle totaled your car in Montgomery and the insurance offer will not cover your loan or your injuries, Barfoot & Schoettker, LLC is available at (334) 834-3444 for a free consultation. We can review the carrier's valuation, the release language, and any injury claim before you sign anything.
Barfoot & Schoettker, LLC · 6771 Taylor Circle, Montgomery, AL 36117 · (334) 834-3444
We are here to help!
Whether it’s the insurance company who refuses to adequately compensate you for your personal injury; the wrongful death of a loved one caused by the carelessness of another; or you've wrongfully been accused of a crime... Regardless of the obstacles you face, we can help.
Call Us Confidentially Now:
(334) 834-3444
Contact Details
OFFICE
6771 Taylor Circle
Montgomery, AL 36117
Phone
Contact Us Today
Use our contact form or give us a call for your no-obligation consultation.